
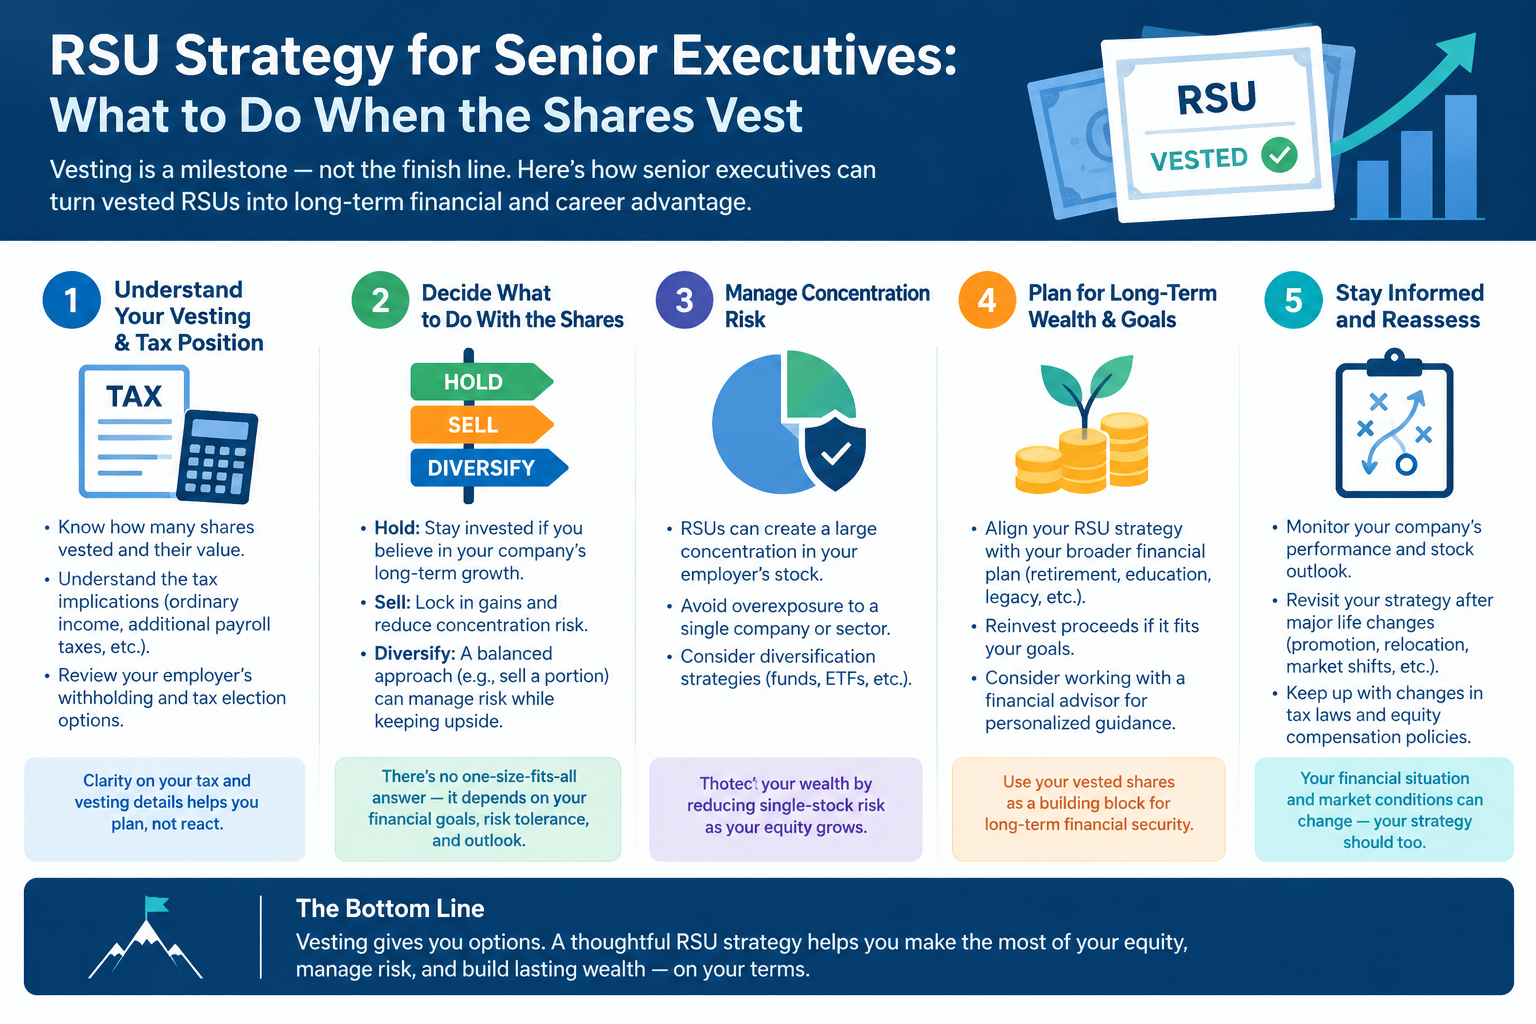
RSU Strategy for Senior Executives: What to Do When the Shares Vest

Ian Richards, Chartered Financial Planner
I help senior leaders turn complex pay & accumulated wealth into a plan to make work optional | Chartered Financial Planner | Work to Live
April 21, 2026
RSUs are one of the most valuable parts of a senior executive's compensation package. They're also one of the most poorly managed.
Most executives have no strategy for what happens when the shares vest which means missing carry-forward opportunities, unexpected pension allowance issues, and wealth sitting in concentrated single-stock exposure with no plan behind it.
This article covers the tax treatment of RSUs in the UK, how vesting income affects the pension annual allowance taper, the carry-forward opportunity and the four decisions that determine whether each vest builds long-term wealth or quietly disappears.
By Ian Richards FPFS · Chartered Financial Planner · Work to Live Financial Planning
Your RSUs vested. The shares appeared in the broker account.
And then, for most executives, not much happened.
Some sold immediately and spent the proceeds. Some held the shares with no clear reason to. Some invested in something that seemed sensible at the time. Almost none had a strategy for when they vesting looking at their pension, their tax position, or the bigger picture of when work could become genuinely optional.
For a senior executive receiving £80,000 in RSUs annually over ten years, those vesting events represent £800,000 in potential wealth before tax. Managed deliberately, a significant portion builds towards the point where work becomes a genuine choice. Managed without a strategy, opportunities are lost, shares are spent, taxed inefficiently, or sitting in concentrated single-stock which brings a great deal of risk.
What RSUs are (and why they create a planning problem)
A Restricted Stock Unit is a promise from your employer to give you a set number of company shares after a vesting period. When they vest, the shares are yours.
But their arrival creates three things at once: a taxable event, a potential pension planning problem, and a decision about what to do with the proceeds. Most executives are prepared for the first. Almost none are prepared for the second and third.
How RSUs are taxed in the UK
When RSUs vest, the market value on the vesting date is treated as employment income typically taxed at 40% or 45% plus NIC. The employer typically withholds shares to cover the liability. The after-tax balance arrives in the account.
If you hold shares after vesting and they increase in value, any gain above the vesting price is subject to capital gains tax. The annual CGT exempt amount is £3,000 for 2024/25. Gains above this are taxed at 18% or 24% depending on total income.
The part most executives miss: RSU income is added to adjusted income for pension taper purposes. Once adjusted income - salary, bonuses, employer pension contributions and RSU vest value combined, exceeds £260,000, the pension annual allowance starts to reduce. Many executives cross this threshold without realising it.
How RSU vesting affects the pension annual allowance
The standard pension annual allowance is £60,000 per tax year. For high earners it tapers, reducing by £1 for every £2 of adjusted income above £260,000, down to a minimum of £10,000.
A year with significant RSU vesting can push adjusted income well above that threshold and dramatically reduce the allowance. At £360,000 of adjusted income, the allowance is at the £10,000 floor. If employer contributions are already high, there may be an annual allowance pension charge to pay on top of the income tax already paid at vesting.
The carry-forward opportunity most executives never use
Unused pension annual allowance from the previous three tax years can be carried forward and added to the current year's contribution capacity. The allowances from three years ago drops off when the new tax year starts, whether used or not.
Most executives who have available allowances never use it.
Here is what it looks like in practice. An executive with £80,000 in RSUs vesting this tax year, adjusted income of £320,000, and £120,000 of unused carry-forward from years where income was lower:
- Annual allowance this year: tapered to approximately £20,000
- Carry-forward available from previous years: £120,000
- Total pension contribution capacity: £140,000
- Pension contribution from RSU proceeds: £80,000
- Income tax saving at 45%: approximately £36,000
Carry forward can allow senior executives who were not previously hit by taper to make substantial pension contributions before you are stuck with the £10,000 tapered threshold after a few years.
Individual illustrative example. Not a recommendation or typical outcome.
It requires knowing the carry-forward position before the vest and acting before end of tax year. Most executives I speak to have significant unused carry-forward they didn't know existed. If you don't use it you lose it.
Why concentration risk matters at every vest
Most senior executives have more of their financial life tied to one employer than they realise. RSUs, SAYE schemes, share options and employer pension contributions are all connected to the same company. Viewed in isolation, each looks manageable. Counted together, the concentration is often significant.
The default case for selling at vesting is strong. Selling removes concentration risk and allows you to diversify your wealth. No matter how strong you think a company is having all your wealth tied up with it is rarely a good idea. Think Blockbuster, Blackberry & Toys R Us.
4 decisions to make at every RSU vesting event
Every vest is a decision. Most executives don’t make them.
Sell or hold? Selling removes concentration risk and creates liquidity. Either is a choice but make sure it is an intentional one.
Pension or ISA? Where carry-forward is available, pension almost always wins. A contribution on RSU could receive income tax relief at 45% or even 60%. An ISA provides no upfront relief but is completely tax-free on the way out. The right answer depends on the specific numbers, your situation and long term plans. A tapered pension allowance may mean ISAs are you main option.
Mortgage overpayment? The right answer depends on your situation. There may be emotional reasons you wish to pay off the mortgage such as feeling of security. Equally investing may generate more long term wealth, understanding the trade offs and modelling can help make this decision
GIA or cash? RSU proceeds sitting in a current account are losing real value. Where pension and ISA allowances are used, a General Investment Account with annual use of the CGT exempt amount could be a good option especially if have a spouse at a lower tax rate.
Before making any of these decisions, one question needs answering first: how much of your financial life is already tied to this company & how comfortable are you with this?
What a deliberate RSU strategy actually produces (based on actual client)
Every RSU vesting event is either a strategic action or a missed opportunity. The difference is a plan.
Dave is 46. Total compensation £280,000. RSUs vesting quarterly. Three old pension pots from previous employers none reviewed, none connected to each other or to the current plan.
Without planning: projected assets approximately £1,000,000.
With a structured RSU strategy, making use of ISAs & paying into a Investment account: projected assets at 60 approximately £2,500,000. Work optional confirmed at 60 if not earlier.
No unusual products. No high-risk strategy. RSU proceeds going to the right place, at the right time, with carry-forward used while it was still available.
The income didn’t change having an actual strategy did.
Individual anonymised example. Not a typical outcome or guarantee. The value of investments can fall as well as rise.
The right starting point
If RSUs are vesting and you don't have a clear strategy for what happens at each event the Clarity Conversation is the right place to start.
Book at worktolivefinancialplanning.com or drop me a DM
Ian Richards FPFS · Chartered Financial Planner · Fellow of the Personal Finance Society · Work to Live Financial Planning Limited · hello@worktolivefp.co.uk · worktolivefinancialplanning.com
This article is for information purposes only and does not constitute financial advice. The value of investments can fall as well as rise. You may not get back the full amount invested. A pension is a long-term investment and its value is not guaranteed. Levels and bases of, and reliefs from, taxation are subject to change. The FCA does not regulate cashflow planning. Work to Live Financial Planning Limited is an appointed representative of ValidPath Ltd, authorised and regulated by the Financial Conduct Authority (FCA Reference Number 197107). Company No. 12059588.


