
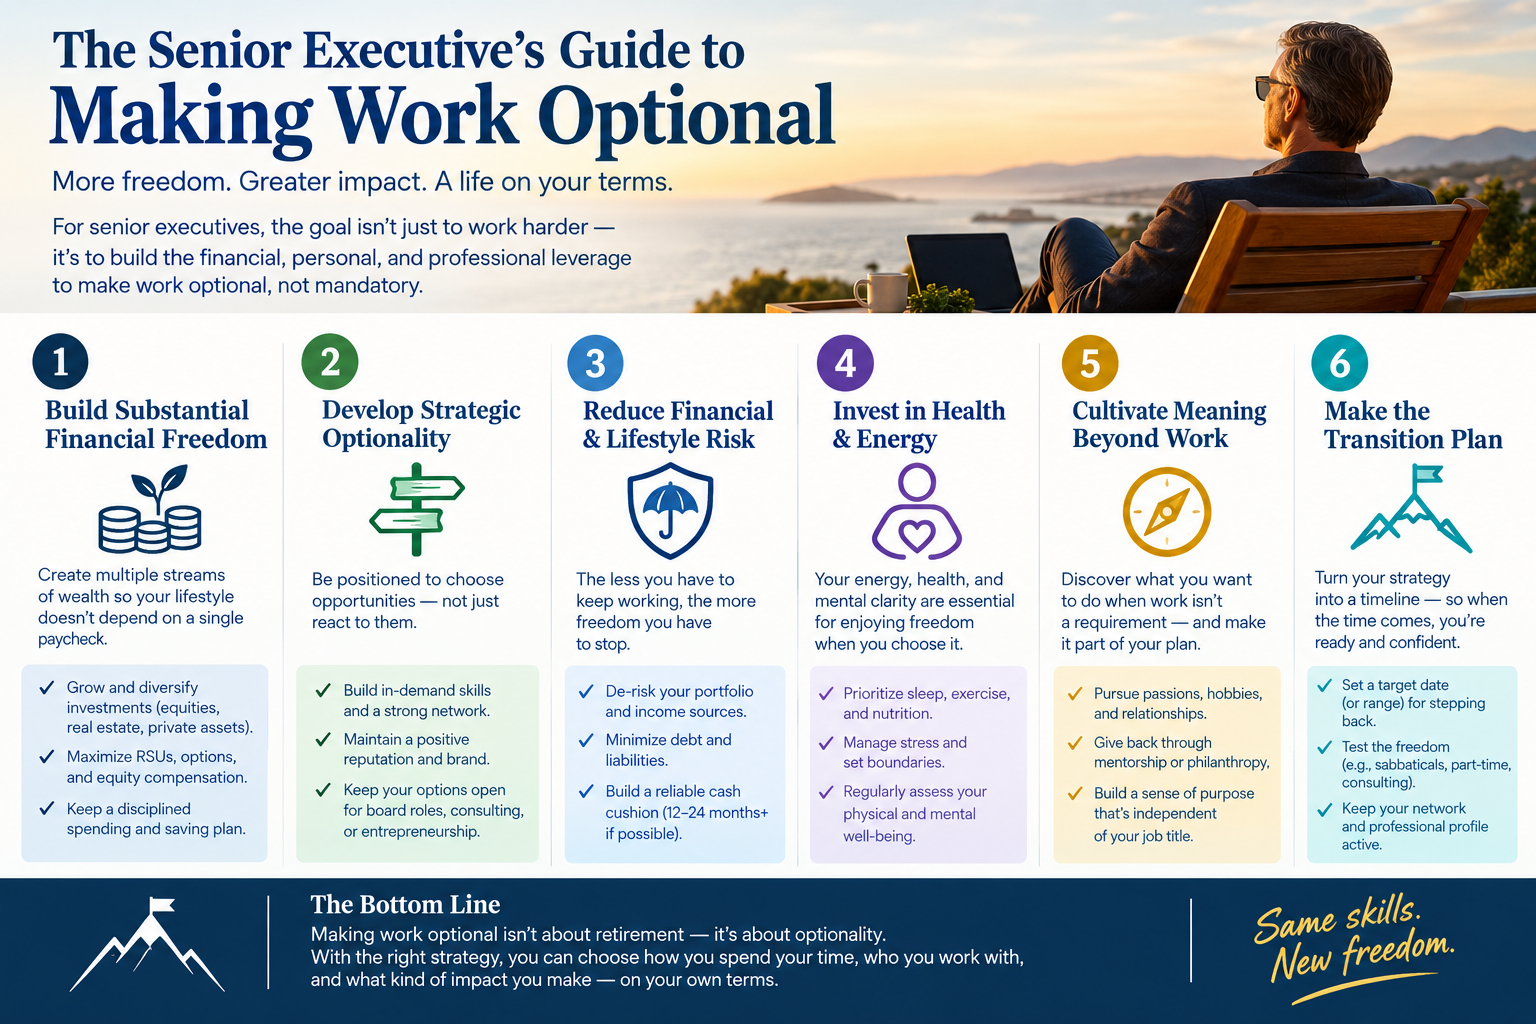
The Senior Executive’s Guide to Making Work Optional
How to turn salary, bonus, RSUs and pensions into one plan — so work becomes a choice, not a requirement. UK edition, 2026/27 tax year.
By Ian Richards FPFS · Chartered Financial Planner · Work to Live Financial Planning
Guide · Make Work Optional · Senior executives · Approx. 20 minute read · Last reviewed September 2026 · Tax year 2026/27
SHORT ANSWER
Making work optional as a senior executive means building enough capital to achieve your Freedom Number so you can fund the life you want at a chosen age, whether or not you keep working. For most executives earning £200,000+, the pieces already exist: salary, bonus, RSUs or LTIPs, several pensions, ISAs. What is missing is one plan that joins them up, uses the allowances before they expire, and reduces reliance on a single employer.
Who this guide is for
This guide is for senior leaders in the UK, usually in their 40s or early 50s, earning £200,000 or more once bonus and equity are included. You probably have RSUs, an LTIP or maybe shares in a company heading for an IPO. You have pension pots. Your income has never been higher. And there is a question you have never quite managed to answer: am I going to be okay?
You are probably not planning to retire. Most of the executives I work with don’t want to stop. They want the choice - a different pace, a portfolio of board roles, less travel, more time with the people they care about. This guide is about building that choice deliberately rather than hoping it arrives.
IN THIS GUIDE
- Why a high income doesn’t feel like control
- What “making work optional” actually means
- Your Freedom Number — and why the 25x rule falls short
- The peak earning window: why your 40s matter so much
- RSUs, LTIPs and share awards: sell, hold, and where the money goes
- Pensions: the annual allowance, the taper and carry-forward
- Pension, ISA, investment account or mortgage — in what order?
- Protection matched to what you earn now
- Stepping back without stepping off a cliff
- Estate planning, including the April 2027 pension change
- Can you spend more now?
- Your tax-year checklist, key figures, FAQs and glossary
Why doesn’t a high income feel like control?
Most senior executives have done everything right. The career has worked. But the financial life has grown in layers, one employer and one decision at a time.
Three pension pots from three employers, each with different charges and nothing connecting them. RSUs vesting with no rule for what happens next. An ISA that put some money into. A mortgage that may or may not be worth overpaying. Protection set up years ago on a lower salary. And no clear answer to when work could become optional.
The money exists. The plan does not.
What does “making work optional” actually mean?
It means reaching a point where you work because you want to, not because you have to. That might mean stopping completely. More often it means working differently: three or four days a week, a non-executive portfolio, consultancy on your own terms, or a long break every year.
My dad worked on his own terms and took two or three months off every year. That was my first picture of financial freedom. Not stopping but choosing. It is the reason my business is called Work to Live, and it is what I see most clients actually wanting.
Money is the fuel, not the destination. The aim is to create a life you don’t want to retire from and to live well now without screwing up the future.
What is your Freedom Number?
Your Freedom Number is the capital you need, at a chosen age, for work to become genuinely optional. It is built from your actual spending, your actual assets and the life you want — not from a multiple of salary.
Why the 25x rule isn’t the full picture work?
The common rule of thumb is to multiply the income you want by 25. Want £80,000 a year? You need £2 million. It is a reasonable conversation starter, but for high earners it misleads in four ways:
- It ignores the State Pension. A full new State Pension is £12,547.60 a year in 2026/27. For a couple both entitled to it, that is about £25,000 of income needing no capital.
- It ignores tax. You spend net income. How you draw from pensions, ISAs and investment accounts changes how much gross income you need.
- It ignores what you already have. A defined benefit pension, rental income or future share vests all reduce the capital you need to build.
- It ignores real spending. Most people underestimate what life costs once they have more time. Travel, hobbies and deferred plans cost money.
How is a Freedom Number actually calculated?
It starts with life, not assets. What does a good year cost? What does work-optional look like for you — fully stopped, two days a week, board roles? At what age does it need to be true? A cashflow model then works backwards across every pension, ISA, investment, share award and liability to find the capital that funds that life for as long as you need it.
In practice it is a realistic ballpark, not a figure to two decimal places. Life changes, so the number is refined every year. It is not a guarantee. But it gives every financial decision a destination and without one, you are deciding about RSU vests, pension contributions and mortgage overpayments without knowing where you are heading.
Why do your 40s and early 50s matter so much?
Because this is the peak earning window — roughly 40 to 55 — when income, tax complexity and time for compounding all peak together. Decisions made now compound for the next thirty years. After 55 the runway shortens.
The cost of drifting through it isn’t visible at the time. It shows up later:
- Pension carry-forward expiring unused every 5 April
- RSU proceeds sitting in cash, spent, or invested with no link to a plan
- Less choices in the future than you could have had
- A work-optional age that arrives at 62 instead of 55
Most people don’t realise they are inside the peak earning window until they are most of the way through it.
What should you do with RSUs, LTIPs and share awards?
For most executives there is no plan for when RSUs vest, some are held, some are sold or life gets in the way and nothing happens.
How are RSUs taxed in the UK?
When RSUs vest, their market value is employment income and taxed accordingly through income tax. Most employers sell enough shares to cover this automatically. Any growth after vesting is a capital gain, taxed at 18% or 24% above the £3,000 annual exempt amount.
How much of your life is tied to one company?
Add it up: salary, bonus, unvested RSUs, LTIP awards, SAYE, the shares you already hold — and the job itself. Each looks good. Together, it is often most of your financial life riding on one share price.
The aim is not to assume the shares will be worth nothing. It is to make sure your future doesn’t depend on one company for everything. For IPO or LTIP exposure, that means building a plan that works with and without the payout. so a good outcome accelerates your freedom and a bad one doesn’t derail it.
When can holding shares make sense?
- The holding is not the majority of your total wealth
- You are in a closed period and cannot sell yet — so plan for when the window opens
- You have looked at the concentration honestly and chosen a set amount to keep
- You understand the tax implications of holding the shares and how fits into wider plan.
If you already hold a large, concentrated position with big gains, selling it all at once can create a large CGT bill. A staged plan across tax years usually works better. The pace should be set by what the money needs to do, not by guessing the share price or hoping for the best.
How much can you pay into a pension?
The standard annual allowance is £60,000 a year, covering your contributions and your employer’s. For high earners it tapers down, and RSU vests make the taper hard to predict.
How does the tapered annual allowance work?
Two income tests decide whether it applies. If your threshold income (broadly taxable income minus personal pension contributions) is £200,000 or less, the taper doesn’t apply. If it is above £200,000 and your adjusted income (taxable income plus employer pension contributions) is above £260,000, your allowance falls by £1 for every £2 over, to a minimum of £10,000.
Adjusted income
Annual allowance (2026/27)
£260,000 or less
£60,000
£290,000
£45,000
£310,000
£35,000
£320,000
£30,000
£340,000
£20,000
£360,000 or more
£10,000 (the floor)
Assumes threshold income is above £200,000. RSU vests, bonuses and employer contributions all count.
Because RSUs vest on dates your employer sets, a large vest late in the tax year can change your allowance with little time to react. The answer is to model the year before the vests happen, not after the tax year closes.
What is carry-forward and why does it matter?
You can add unused allowance from the previous three tax years to this year’s allowance, as long as you were a member of a registered pension scheme in those years. The oldest year is lost after 5th April each year. For many executives — especially those promoted recently — this is the biggest single opportunity in their plan.
ILLUSTRATION
An executive’s adjusted income is £320,000 this year, including an £80,000 RSU vest. Her allowance tapers to £30,000. She has £120,000 of unused allowance from her pre-promotion years, so her total capacity is £150,000.
After tax, the vest leaves about £42,000. She sells the shares and pays that into her pension. Basic-rate relief takes it to about £53,000, and she reclaims roughly £13,000 more through her tax return — around £24,000 of relief in total. She still has room to top up from her bonus before 5 April.
Illustrative example only, not a real client. Not a recommendation or typical outcome. Figures based on 2026/27 rules.
Can you avoid the taper altogether?
Sometimes. Because personal contributions reduce threshold income, a large enough personal contribution can bring threshold income to £200,000 or below, which switches the taper off for that year. Salary sacrifice set up after 8 July 2015 doesn’t work the same way - the sacrificed salary is added back. This needs careful planning before any large contributions are made.
Pension, ISA, investment account or mortgage — in what order?
The right order depends on what the money is for and when you need it. A sensible starting sequence for most executives is:
- Cash buffer — three to six months of spending, so markets never force a sale.
- Pension, including carry-forward — the strongest tax relief available, but locked until 55 (57 from 6 April 2028).
- ISAs — £20,000 each a year. No upfront relief, but tax-free growth and access. For a couple over ten years, that is £400,000 of contributions sheltered from tax.
- General investment account — for surplus beyond allowances, using the £3,000 CGT exemption each year and a lower-rate spouse where appropriate.
- Mortgage overpayments — worth modelling against investing. Wanting the security of no mortgage is a legitimate reason.
The key point: if you want work to be optional before your mid-50s, you need money you can access before pension age. Pouring everything into pensions could leave you with a big gap.
How do you step back without stepping off a cliff?
By funding the bridge. If a non-executive portfolio pays a third of what you earn now, something has to fill the gap until pensions can be drawn. That bridge could come from ISAs and investment accounts funded by earlier RSU vests.
ILLUSTRATION
A household needs £110,000 a year. A portfolio of board roles pays £60,000. That leaves £50,000 a year to find until pension access at 57. Stepping back at 52 means a five-year bridge of roughly £250,000 before growth and tax — held outside pensions.
Illustrative example only, not a real client. Not a recommendation or typical outcome. Figures based on 2026/27 rules.
Can you spend more now?
Often, yes. One of the most common things I hear from high earners is that they feel guilty spending money despite saving well. The same cashflow model that produces your Freedom Number also shows what you can afford to spend now without damaging the future.
For many clients that is the most valuable output of the whole plan — permission. The extra holiday, the sabbatical, the kitchen, the years with young children that don’t come back. Planning isn’t only about protecting the future. It is about not deferring your life.
A couple I work with no longer need to retire. One works three days a week, the other four. More padel, more travel, more time together. They didn’t get there by earning more. They got there by deciding what they wanted and pointing the money at it.
What does a joined-up plan look like in practice?
CLIENT EXAMPLE
Dave, 46. Total pay £280,000 with RSUs vesting quarterly. Three old pension pots, none reviewed. Mortgage with eight years left.
Projected assets at 60 before planning: about £1 million. With a structured RSU strategy, carry-forward pension contributions and a systematic ISA plan: about £2.5 million, with the cashflow model indicating work could become optional at 57.
No unusual products. No high-risk strategy. The income didn’t change. Having a plan did.
Anonymised client example based on illustrative cashflow projections. Not a guarantee or typical outcome. The value of investments can fall as well as rise
Your tax-year checklist
Use this each year. Most of the value in executive planning comes from doing ordinary things at the right time.
When
What to do
April–May (new tax year)
Fund ISAs early. Note this year’s vesting schedule and expected bonus. Estimate adjusted income.
Before each vest
Decide your standing rule: sell-to-cover, sell the rest, and where proceeds go. Check your closed periods.
Mid-year review
Update the cashflow model. Check your concentration in employer shares. Review protection against total pay.
January–February
Confirm adjusted and threshold income. Calculate your tapered allowance. Map carry-forward for the last three years.
By 5 April
Make pension contributions to use this year’s allowance and the oldest carry-forward year before it expires. Use the CGT exemption.
Every 2–3 years
Review wills, LPAs, beneficiary nominations and your inheritance tax position.
Key figures for 2026/27
Item
2026/27 figure
Pension annual allowance
£60,000
Taper thresholds
Threshold income £200,000 · Adjusted income £260,000
Minimum tapered allowance
£10,000 (adjusted income £360,000+)
Carry-forward
Unused allowance from the previous 3 tax years
Money purchase annual allowance
£10,000 once you draw flexibly from a pension
ISA allowance
£20,000 per person
CGT annual exempt amount
£3,000 · rates 18% / 24%
Personal allowance
£12,570, withdrawn between £100,000 and £125,140
Additional-rate income tax
45% above £125,140
Minimum pension age
55, rising to 57 from 6 April 2028
Tax-free pension cash
25%, capped at £268,275 for most people
IHT nil-rate band / residence nil-rate band
£325,000 / £175,000 (tapered above £2m estates)
Pensions and IHT
Most unused pensions count towards the estate from 6 April 2027
Scottish income tax rates differ. Figures should be confirmed against current rules before acting.
Frequently asked questions
What is financial planning for senior executives?
It is the process of joining up salary, bonus, share awards, pensions, protection and investments into one strategy built around a specific goal — usually the point at which work becomes optional. Life-first planning starts with the life you want and builds the financial plan to serve it, rather than starting with products.
Should I sell my RSUs when they vest?
For most executives, selling as they vest is likely to be sensible. Income tax is paid at vest whether you sell or not, so holding is an active decision to invest in your employer. Holding can make sense if the amount is small, you have a shareholding requirement, or you have deliberately chosen to keep a set amount.
Do RSUs affect my pension annual allowance?
Yes. The value of RSUs at vest counts as employment income, so it adds to both threshold and adjusted income. A large vest can push adjusted income above £260,000 and reduce your allowance, even if your salary alone would not.
How much can a high earner pay into a pension in 2026/27?
The standard annual allowance is £60,000, tapering to a minimum of £10,000 once adjusted income reaches £360,000. Unused allowance from the previous three tax years can be carried forward, which can allow a much larger contribution in a single year.
What is a Freedom Number?
Your Freedom Number is the capital you need, at a chosen age, for work to become optional. It is calculated from a cashflow model using your real spending, assets, pensions and target age — not a multiple of salary or the 25x rule.
Can I retire before I can access my pension?
Yes, if the years before pension access are funded from ISAs, investment accounts, part-time income or cash. The minimum pension age is 55, rising to 57 from 6 April 2028, so planning the bridge is usually the first job for anyone stepping back early.
Will my pension be subject to inheritance tax?
From 6 April 2027, most unused pension funds and death benefits will be included in your estate for inheritance tax. Death-in-service benefits from registered schemes are excluded. This makes reviewing your estate plan and beneficiary nominations more important for executives with large pensions.
Is my employer income protection enough?
Often not. Most group policies are based on base salary only and ignore bonus and share awards. If your total pay is well above your base salary, there may be a significant gap between your cover and what you would lose if you couldn’t work.
Do I need a financial planner if I understand money?
Not necessarily, it depends on various factos. The value of a planner is usually in joining the pieces up, helping your understand your priorities and modelling the trade-offs, spotting deadlines like carry-forward, and giving you a second opinion you can trust when the stakes are high.
Glossary
Term
What it means
Adjusted income
Taxable income plus employer pension contributions. Used to calculate the tapered annual allowance.
Threshold income
Broadly taxable income minus personal pension contributions. If £200,000 or less, the taper does not apply.
Carry-forward
Using unused pension allowance from the previous three tax years in the current year.
RSU
Restricted Stock Unit — a promise of company shares that vest over time and are taxed as income at vest.
LTIP
Long-Term Incentive Plan — share awards that vest if performance conditions are met, usually over three or more years.
Sell-to-cover
When your employer sells part of a vest to pay the income tax and NI due.
Freedom Number
The capital needed, at a chosen age, for work to become optional.
Peak earning window
Roughly ages 40–55, when income, tax complexity and time to compound all peak together.
GIA
General Investment Account — a taxable investment account for money beyond ISA and pension allowances.
ABOUT THE AUTHOR
Ian Richards FPFS is a Chartered Financial Planner and Fellow of the Personal Finance Society, and the founder of Work to Live Financial Planning. He works with senior executives, equity partners and business owners who have built real wealth and want a joined-up plan that makes work optional.
Ready to join it all up?
If you are a senior executive and nobody has ever joined the full picture up for you, a Discovery Call is the place to start. We’ll look at where you stand, what the next few vests and tax years could do, and whether the Work to Live Blueprint is worth it for you. I’ll tell you honestly if it isn’t.
Book a Discovery Call · worktolivefinancialplanning.com
Not ready to talk? Take the Make Work Optional Scorecard to see where you stand in a few minutes.
This content is for information purposes only and does not constitute financial advice, which should be based on your individual circumstances. The value of investments can fall as well as rise and you may not get back the full amount invested. A pension is a long-term investment and its value is not guaranteed. Levels and bases of, and reliefs from, taxation are subject to change and depend on individual circumstances; figures quoted are for the 2026/27 tax year and should be confirmed before acting. The FCA does not regulate cashflow planning, tax planning or some aspects of estate planning. Illustrative examples are not typical outcomes. Work to Live Financial Planning Limited is an appointed representative of ValidPath Ltd, authorised and regulated by the Financial Conduct Authority (FCA No. 197107). Company No. 12059588.


